中国通缩之殇:从流动性陷阱到经济系统性危机
China's Persistent Deflation: An Analysis of the Economic Downturn
China’s Consumer Price Index (CPI) has remained in the deflationary range for over two years. Despite this prolonged trend, the central bank has firmly denied the existence of deflation. Earlier this year, former central bank governor Yi Gang indirectly acknowledged the issue by admitting to “insufficient demand” without explicitly recognizing deflation.
Strictly speaking, China does not meet the textbook definition of deflation, as the money supply has not decreased, and credit has not tightened. However, as Bloomberg noted in a March 2024 article reprinted by Lianhe Zaobao, “China’s Liquidity Trap Looms: Financing Costs Falling Across Markets,” despite two policy rate cuts over the past year, loan growth in January hit a record low. With weak confidence, consumers and businesses are holding onto cash. Economist Liu Yuhui aptly described the situation as a collapse in the money multiplier: no matter how much money is injected into the system, it proves ineffective.
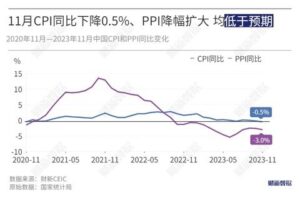
The continuous decline in the Producer Price Index (PPI) already confirms that China is, in fact, experiencing deflation. Aside from state-controlled utilities like water, electricity, and gas, the overall price level across society has been on a clear downward trend. Investment opportunities with attractive returns are virtually nonexistent, and even the once-booming auto industry has entered a wave of layoffs. As economist Gao Shanwen remarked, “When a nation is in decline, nothing seems to go right.”
The majority of people are facing a steady decline in income and income expectations. Society as a whole has entered a "disaster-prevention mode," where people avoid spending money, causing the money multiplier to collapse. When no one spends, you cannot earn from me, and I cannot earn from you. Money circulation stagnates, and there are no profitable investment opportunities.
The data from November merely reiterates what has been happening monthly over the past two years: China has entered a deflationary death spiral.
Severe Wealth Inequality
China's monetary and savings landscape is highly polarized. Those without money desperately need it but cannot repay loans due to a lack of profit-generating opportunities in the economy. Meanwhile, those with wealth see no reason to borrow. This creates an unsolvable dilemma.
Will the government distribute money to those in need? Unlikely.
While residents’ savings total 150 trillion yuan, averaging over 100,000 yuan per person, the reality is stark: 800 million people are in debt, 400 million have overdue payments, and a tiny fraction controls the vast majority of personal savings. No matter how consumption is stimulated, it cannot gain traction.
Even if interest rates were reduced to zero, investment enthusiasm would not recover. Wealthy individuals, already a minority, contribute little to overall consumption, and many are looking to leave the country.
Predictable Outcomes
Looking ahead, except for medical care and elderly care, prices across society are likely to continue declining. With businesses unprofitable, there will be no new investments or additional employment opportunities. This is evident from the low employment rates among college graduates. Economist Liu Yuanchun predicts that youth unemployment will remain high for a decade, describing it as a systemic and structural trend. In other words, the economic problems are long-term and deeply entrenched. In such a climate, imagining a hopeful "future" becomes a luxury.
Without reforming the distribution system and addressing secondary distribution, merely increasing taxes will not solve the problem. China’s overall tax burden is already high. If redistribution reforms are avoided, the only option will be to target the wealthy for higher taxes.
Robbing the Rich?
In a deflationary context, deposit interest rates must remain below the CPI inflation rate, effectively turning negative. With CPI already negative and deposit rates still positive, the real interest rate is high. To "rob" the rich, policies could include eliminating interest on deposits and imposing a 2-3% management fee, or levying a 30-45% tax on pensions exceeding 10,000 yuan. Such measures, however, would directly antagonize the bureaucratic elite.
The Fragility of Governance
Recent protests in the UK by farmers opposed to tax hikes carried slogans like, "We can do without the government, but we cannot do without farmers." In China, the situation is different. With a large number of agitated individuals and potential unrest, the government’s absence could lead to chaos. Without strong governance, society could spiral into disorder.
For now, the "sheep" are urged to hold on, show confidence, and understand the government’s challenges.